The math nobody explains at the bank
I've had three conversations this fall that all started the same way. A homeowner bought or refinanced in 2020 or 2021, locked in a rate somewhere around 3%, and now needs money. A kitchen that's falling apart. A kid starting college. Credit card debt that crept up. A down payment for a second property. And every one of them assumed the only way to get at their equity was to sell the house.
That's just not true. And it's not even close to the smartest move for most of them.
Here's the thing most people don't realize: your first mortgage and your home equity are two completely separate assets. You can borrow against the equity without touching the mortgage at all. The rate you locked in back in 2021 stays exactly where it is. You just add a second loan on top, priced at today's rates, against the portion of the house you actually own outright.
So the question becomes: why would anyone refinance their entire mortgage balance at today's rate just to pull out a portion of it in cash? Basically, they wouldn't. Not if they understand what's actually happening to the math. That's the whole game.
Cash-out refinance: the option that resets everything
A cash-out refinance replaces your entire existing mortgage with a brand new one, at a higher loan amount, at whatever rate is available today. If you owe $200,000 at 3% and want $50,000 in cash, you're not borrowing $50,000 at today's rate. You're refinancing the whole $250,000 at today's rate.
That's the part people miss. You're not just paying a higher rate on the new money. You're paying a higher rate on the entire existing balance too. On a 3% to 4% loan that still has 25+ years left, that swap can cost you tens of thousands of dollars over the life of the loan, just in the rate difference on money you already had financed cheaply.
I'm not saying cash-out refis never make sense. If you need a very large sum - more than a HELOC or home equity loan would reasonably get you, or more than your lender's combined loan-to-value limits allow on a second lien - a cash-out refi might be the only path. But for most of the homeowners I talk to who need $30,000 to $100,000 for a project or a debt payoff, giving up a 3% rate on their whole mortgage to do it is a bad trade. I'd tell any client that directly.
HELOC vs. fixed home equity loan - the real difference
Once people rule out refinancing the whole mortgage, they're choosing between two tools that both let the original 3% rate sit untouched. A HELOC and a fixed home equity loan solve different problems, and the difference matters more than people expect.
- HELOC (home equity line of credit): Works like a credit card secured by your house. You get approved for a credit limit, draw what you need when you need it, and only pay interest on what you've actually used. The rate is usually variable, tied to the prime rate, so your payment moves as rates move.
- Fixed home equity loan: You borrow a lump sum up front, at a fixed rate, and pay it back on a set schedule - basically a second mortgage. The rate doesn't move. The payment doesn't move.
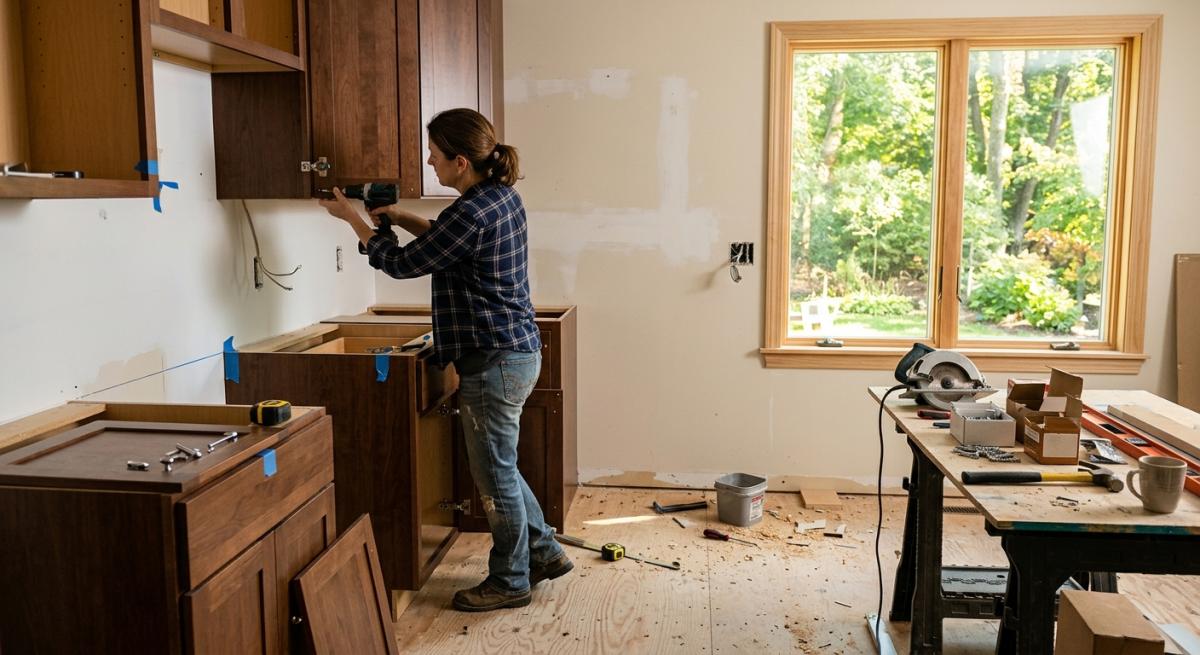
The HELOC is the right tool for a project with an unknown total cost - a kitchen renovation where you're not sure if it ends at $40,000 or $65,000 once you open up the walls. You draw as you go. You're not paying interest on money sitting unused.
But the fixed home equity loan fits a known number. Tuition due at a specific amount. Debt payoff where you know exactly what you're consolidating. A down payment on a second property. If you know the number, lock the rate. Don't leave it floating for no reason.
The CT wrinkles people don't see coming
Connecticut has a few specifics that catch people off guard, and I'd rather explain them now than have a client surprised at closing.
A HELOC or home equity loan gets recorded as a second mortgage at the town clerk's office in whatever town the property sits in - Southington, Berlin, Newington, wherever you are. That recording establishes lien priority. Your original mortgage holder stays in first position, meaning they get paid first if the home is ever sold or foreclosed. The new lender is in second position. This is standard, but it's why the lender will order a title search before closing, even though you already have an owner's title policy from your original purchase or refinance. That existing policy protected you and your original lender at that time - it doesn't automatically extend to protect a new second lienholder. The new lender typically requires its own search and sometimes its own lender's title policy to confirm nothing has attached to the property since you last closed - a tax lien, a judgment, a contractor's lien.
Closing costs on a HELOC or fixed home equity loan are real, but smaller than a full refinance, because you're not originating a brand new first mortgage on the full balance. Expect an appraisal ($400-$700), a title search ($200-$500), recording fees at the town clerk (~$60-$100), and often a smaller attorney involvement than a full purchase or refi closing requires. It's not free. But it's a fraction of what you'd pay refinancing the whole mortgage.
One more thing worth asking your lender directly: whether interest on a home equity loan or HELOC is tax-deductible depends on what you use the money for and how the IRS currently treats that use. The rules have real conditions attached. Don't take a blog's word for it - ask your CPA or your real estate attorney before you assume any of it is deductible.
Why this is the move right now, not a workaround
CT's market right now is a supply problem more than anything else. People with 2-3% mortgages locked in during 2020 and 2021 are not selling, because moving means giving up that rate and paying a lot, lot more on a replacement home at today's rates. That's exactly why inventory is so tight in towns like Southington, Berlin, and Newington. And it's exactly why so many of those same homeowners are choosing to improve or leverage the house they're in rather than sell it.
Tapping equity through a HELOC or fixed home equity loan isn't a consolation prize. For someone who needs money for a renovation, tuition, debt, or a down payment on a second place, and who has no interest in giving up a mortgage rate they'll probably never see again, it's the better math, full stop. You keep the cheap money on the big balance and only pay today's rate on the smaller amount you actually need. That is the whole game.
I had a seller once who was debating whether to finish an attic before listing. I ran the numbers across a few scenarios, and the renovation paid for itself and then some once it was done, because it opened the house to a different pool of buyers entirely. Same logic applies here, just without the
Frequently Asked Questions
Can I get a HELOC if my home has a lot of equity but my credit score isn't perfect?
Lenders look at combined loan-to-value, income, and credit together, so a lower score doesn't automatically disqualify you if your equity position is strong. It may affect your rate or the credit line amount offered, so it's worth shopping more than one lender.
Does a HELOC or home equity loan affect my original mortgage rate?
No. Your first mortgage stays exactly as it is, same rate, same term, same lender. The HELOC or home equity loan is a separate second mortgage recorded behind it at the town clerk's office.
Is a HELOC or a fixed home equity loan better for a kitchen renovation?
A HELOC usually fits better when you don't know the exact final cost, since you only draw and pay interest on what you use. If you've already got a fixed contractor quote, a fixed home equity loan locks in your rate and payment with no surprises.
How much equity do I need before a lender will consider a second mortgage?
Most lenders want to see meaningful equity remaining after the new loan, often requiring your combined mortgage balances to stay well under the home's appraised value. The exact threshold varies by lender, so get a few quotes before assuming you don't qualify.
Is the interest on a HELOC or home equity loan tax-deductible in Connecticut?
It depends on what the loan proceeds are used for and current IRS rules, which have specific conditions attached. Talk to a CPA or real estate attorney before assuming any interest is deductible - don't rely on a general blog post for that answer.